
Closed for Columbus Day

Our office will be closed Monday, October 12 in observance of Columbus Day.
We will reopen Tuesday, October 13 during our regular business hours.

Our office will be closed Monday, October 12 in observance of Columbus Day.
We will reopen Tuesday, October 13 during our regular business hours.


Bring your unwanted sensitive documents and have them securely shredded.


Scam calls are nothing new, but they are becoming increasingly convincing.
Today’s scammers may impersonate banks, government agencies, utility companies, insurance providers, delivery services, or even people you know. They can also manipulate caller ID information to make a call that appears to come from a familiar or legitimate phone number.
Knowing what to watch for can help you protect your personal information and finances.
Be cautious anytime an unexpected caller asks you to provide sensitive information, send money, or take immediate action.
Legitimate organizations generally will not unexpectedly call and demand passwords, PINs, verification codes, or other sensitive account information.
If you are unsure, hang up and contact the organization directly using a phone number you know is legitimate.
Seeing a familiar name or local phone number on your screen does not necessarily mean that’s who is calling.
Scammers can use a technique known as “spoofing” to disguise the number they are calling from. They may even make a call appear to come from your bank, a government agency, or another trusted organization.
Treat the caller’s behavior, not simply the number on your screen, as the better indication of whether a call is legitimate.
Scammers often try to create fear or urgency.
They may claim that your account has been compromised, you owe money, a family member is in trouble, or something bad will happen if you do not act immediately.
That is a good reason to slow down.
Hang up, verify the situation independently, and never allow an unexpected caller to pressure you into making a financial decision.
Requests for unusual payment methods should raise an immediate red flag.
Be especially cautious if someone asks you to pay using gift cards, cryptocurrency, wire transfers, or other methods that can be difficult to reverse.
Information such as your Social Security number, date of birth, account numbers, passwords, and verification codes can be extremely valuable to criminals.
Do not provide sensitive information to someone who contacts you unexpectedly. When in doubt, end the conversation and independently contact the organization the caller claims to represent.
Scammers rely on getting people to react quickly. Taking a moment to stop, question the situation, and verify who you are dealing with can make a significant difference.
Protecting yourself financially also means periodically reviewing the safeguards you already have in place.
At Thorp & Trainer Insurance, we are here to help you understand your insurance coverage and make sure it continues to meet your needs. If it has been a while since you have reviewed your policies, or you have had changes in your home, family, vehicles, or business, contact our team for a coverage review.

In this issue: We are sharing an important reminder about premium payment timing and why keeping your account current can help support a smoother renewal process.
Insurance carriers review several factors when determining renewal pricing, terms, and eligibility. Along with claims history, coverage needs, business operations, and market conditions, some carriers may also consider payment history.
A pattern of late premium payments can signal increased billing risk. At renewal, that history may contribute to higher premiums, less favorable payment options, or additional underwriting review.
A few simple billing habits can help reduce the chance of late fees, cancellation notices, and renewal-related concerns:
If you have questions about your billing schedule, payment options, or a notice received from the carrier, please contact our office as soon as possible. Addressing billing concerns early may help avoid unnecessary fees, cancellation activity, and possible impacts to your renewal terms.
Renewal Reminder: Timely premium payments help demonstrate account reliability and may support better renewal outcomes.

This article explains how 100 year floods actually work.
FC&S Editors | June 29, 2023
The Truth about 100-Year Floods
Whenever a strong hurricane or storm causes significant flooding, there is often talk of a 100-year flood. When people hear this term they think a flood of that magnitude occurs once every hundred years, so they should be safe from harm for the next hundred years. Unfortunately, some base their decision to buy flood insurance on this false belief, putting them at risk of a catastrophic loss.
The reality of this is different. It involves frequency analysis and statistical probability. In order to determine the frequency of floods of a given level, scientists create a history of the area. Generally, scientists start with a minimum of ten years of information. The longer the record, the better and more accurate predictions. They look at the frequency of different size floods and the average number of years between them in order to develop the probability of a given size flood in any given year.
In order to consider a flood extreme, experts start by determining the normal amount of rainfall and stream stage for a given body of water. Stream stage is the level of water, measured in feet, above a certain arbitrary point. The measurement is the distance from the riverbed to the height of the water. A stream or river in normal conditions could have a stage of two feet, meaning the stream is two feet deep. If a big storm hits suddenly the stream stage could quickly rise to fifteen or twenty feet. A flood occurs when the stream or river overtops the natural or artificial banks of the stream. Rain volume alone does not always create a flood; the condition of the ground before the rain starts is critically important. Has the area received a lot of rain recently and is the ground already saturated? Less rain is needed to create a flood under those conditions. Likewise, if the area has been under a drought and the rain is falling fast, it is possible for the water to run off instead of soaking into the ground. This can lead to mud and landslides, depending on the ground in the surrounding area.
If a river basin is altered such that it affects the flow of water, scientists will re-evaluate the frequency. The addition of dams and levees will change the odds. Once a flood has receded, high-water marks are surveyed to estimate maximum flows that cannot be measured during an active storm. Streamgauges record the height and quantity of flow. As rivers and streams flow and flood, the beds and flow of water change causing sediment to flow downstream and the bed itself to change, which can change the flow of water.
The accumulation of data allows for a determination of the annual probability that a given stream or river will exceed its banks. This is known as annual exceedance probability or AEP. A one-percent AEP flood has a 1 in 100 chance of occurring every year, with an average recurrence every 100 years. This is the 100-year flood. A 500-year flood has an AEP of 0.2 percent chance, or a one in 500 chance of occurring in any given year. It is entirely possible for there to be 100-year or 500-year floods in consecutive years. Because of the confusion and misunderstanding the term 100-year flood generates, the United States Geological Survey is encouraging the use of the AEP terminology, so the phrase 1-percent AEP flood is preferred over a 100-year flood. During the span of a thirty-year mortgage, there is a 26 percent chance of a home in a 1-percent AEP, or 100-year flood area, being flooded.
The National Weather Service provides a calculator so it can be determined just how often a storm of a given strength will occur over a given time period. In the following chart we have calculated the risk of a 100-year and other floods over 1, 10, 20, 30, and 50 years.
|
Time |
10 year flood |
25 year flood |
50 year flood |
100 year flood |
Total Percent Risk |
|
1 year |
10% |
4% |
2% |
1% |
17% |
|
10 years |
65% |
34% |
18% |
10% |
127% |
|
20 years |
88% |
56% |
33% |
18% |
195% |
|
30 years |
96% |
71% |
45% |
26% |
238% |
|
50 years |
99% |
87% |
64% |
39% |
289% |
As you can see, areas susceptible to a 1% chance of a 100-year flood are at significant risk of some type of water incident much sooner than 100 years; at the ten-year mark, the chances of some sort of water damage is 127%. If I had a 127% chance of winning the lottery I’d definitely buy a ticket. At 20 years the chance of some water damage is 195%. It may not be catastrophic, but water damage is expensive, especially in warmer climates where mold can grow quickly and cause even more damage.
Original September 2017
While theft is covered under your homeowners insurance, the mysterious disappearance of a valuable item might not be.
Personal lines property policies, such as renters, condo and homeowners insurance, include some level of coverage for personal belongings in cases of vandalism or theft. That coverage can be used to insure things like jewelry or electronics, and usually has a dollar limit of around $1,000 to $2,000.
But there is a lesser-known issue that may come up when filing a personal property claim for stolen or lost valuables. This is known as the “mysterious disappearance” exclusion.
The mysterious disappearance clause allows insurers to deny claims when an item goes missing under mysterious circumstances. These cases often involve a claim of loss when there is no evidence of theft — for example, nothing else was stolen, no police report was filed and there is no indication of forced entry.
The exclusion is designed to protect insurers in cases where someone loses or forgets an item somewhere like a hotel room. It also is designed to protect insurers against fraudulent claims that an expensive item was stolen.
Not all home insurance policies contain this exclusion, so it’s best to understand your policy before signing on. If your insurance does contain a mysterious disappearance exclusion, it is still possible to protect the value of your special possessions against unexplained losses.
You may do this by adding a property policy endorsement, also known as a policy rider or personal articles floater, to your homeowners, renters or condo insurance. Doing so will allow you to “schedule” your valuables, or list the items. Jewelry is the most common, but art work, furs and firearms are other typical scheduled belongings. Any item included in the floater policy will typically be covered, including if it goes missing or is stolen. The floater will even cover the items while you are traveling.
If you are specifically interested in insuring jewelry, it is possible to get a stand-alone jewelry insurance policy. Such a policy may provide adequate coverage if a high-value piece mysteriously disappears. There may be a time limit on reporting the loss, so check the details of your policy. And know that some insurers require you to surrender the piece or return the payout if the item reappears after a claim is paid. Depending on the circumstances and the item’s value, the insurer may also investigate the claim of a mysterious disappearance.
It is important to note that you may need a professional appraisal before a carrier will bind floater coverage. This ensures your items are covered at the correct value.
It is best to work with your account manager on creating an inventory of your valuables. This will help you determine if your current property policy provides enough coverage for these items or if buying a personal articles floater is the right option for you. If you have high-value belongings, discuss them with your insurance agent. They can help you choose from the best policy options available and avoid surprise exclusions.
According to the National Oceanic and Atmospheric Administration (NOAA):
The Atlantic hurricane season peaks in late summer, but it lasts from June 1 to Nov. 30. The right side of a hurricane is often the most destructive.
Winds can extend as far as 300 miles from the center.
The size of a hurricane is not an indication of its intensity. A small but strong hurricane can cause as much damage as a large but weak one.
In a three-year period, an average of five hurricanes hit the U.S. Two of them are severe.
Hurricanes typically form in the Atlantic and Pacific tropics because they require warm water (at least 79 F) to form.
The eye of a hurricane is relatively calm with no clouds. The area around it, the eye wall, is the most dangerous. The eye wall is a ring of clouds and thunderstorms surrounding the eye.
A hurricane watch means hurricane-force winds are possible. A hurricane warning means hurricane force winds are expected. A watch is issued 48 hours before the anticipated onset, while a warning is issued 36 hours before.
The best time to prepare for hurricane season is now. Here are eight hurricane preparation tips from Ready.gov to get you started:
The biggest threat to inland areas when a hurricane hits is flooding. Hurricanes can cause rains exceeding 6 inches. And just 1 inch of water can cause $25,000 in damage, according to FEMA.
However, floods aren’t covered under homeowners or renters insurance. You need a separate flood insurance policy to cover flood damage. You can buy it through the National Flood Insurance Program or a private insurer.
Ask your agent to help you find the right policy for your needs.
Driving during the summer, especially over a holiday weekend, increases your odds of being in an accident. That’s because of the high volume of cars on the road, roadwork, impaired drivers and erratic driving behavior.
Summer is also when teen drivers hit the roads in force. AAA refers to the 100 days between Memorial Day and Labor Day as the “100 Deadliest Days for Teen Drivers,” given the dramatic increase in fatal crashes involving teen drivers during that stretch.
Here are some tips to help you stay safe on the road this summer.
Fatigue can affect any driver. Summer driving often involves long distances, and everyone is anxious to get to their destination. Even so, it’s not worth the risk. Approximately 20% of all motor vehicle crashes involve drowsy driving, according to the National Sleep Foundation (NSF).
Driving for extended periods can create the same responses as someone driving under the influence of drugs or alcohol. A clinical trial conducted by the NSF found that being awake for 17-19 hours is comparable to having a blood alcohol content of .05%. Both result in decreased reaction time and hand-eye coordination. When participants went beyond 19 hours without sleep, their driving performance levels were equivalent to a blood alcohol content of .1%.
Signs of drowsy driving include:
Heavy eyelids or blinking a lot
Excessive yawning
Drifting between lanes
Missing road signs or exits due to daydreaming
Restlessness, irritability and aggressiveness
Don’t drive while your body is naturally drowsy, between 12-6 a.m. and 2-4 p.m. When you feel fatigued, stop and rest. Take a 20-minute power nap or walk around for a few minutes to get your blood flowing. Use this time to check your vehicle’s tire pressure and fluid levels.
To stay alert during your trip, play music or listen to a podcast or audiobook. Some people choose music they don’t like because it prevents them from being lulled into a road trance. Others choose music that motivates them to sing, move and get their adrenaline pumping.
Another option is to lower the temperature. You don’t want it so cold that you’re shivering, but keeping the AC cooler than normal can discourage sleepiness.
If you’re so sleepy that your eyes close or you nod off, find a safe place to pull over and rest.
On long car rides, it’s easy to become distracted or bored. You might be tempted to call or text a family member or shop online. Other drivers, road construction, changes in scenery and kids in the back seat can also be distracting.
To avoid becoming distracted, plan ahead. Pack games, snacks for the kids and anything else you need for a comfortable trip. If a child needs your attention, pull over. Also, avoid eating while driving and keep your phone out of reach and out of sight to discourage texting. Set your device to auto-respond to texts and use a hands-free solution if you must take voice calls.
The longer the drive and the later in the day you are driving, the more likely you are to encounter an impaired driver.
If you notice another driver weaving or driving erratically, put as much distance as possible between their car and yours. If you have a passenger, ask them to record the license plate number and vehicle information. Then have them call 911 to report the suspected impaired driver.
Summer can bring thunderstorms, heavy winds, flooding, hail and other dangerous driving conditions. Before you leave, check the weather forecast and prepare your vehicle. Examine your windshield wiper blades, battery, tire pressure and tire tread. And clean your car’s external camera.
If you find yourself in slippery conditions, the National Safety Council offers this advice:
If you find yourself in foggy conditions, the National Weather Service recommends you:
Fog can develop fast and change rapidly. Visibility may be lower near rivers, lakes and marshes. If you have to pull off the road, signal first. Pull off the road as far as you can safely go. Then turn on your hazard flashers so others can see you. When merging back into traffic, signal your direction. Give yourself and other drivers plenty of space and time to adjust to your vehicle reentering the road.
Summer brings lots of activities and fun, but also dangers. By preparing and practicing defensive driving, you can enjoy your trip and arrive at your destination safely.
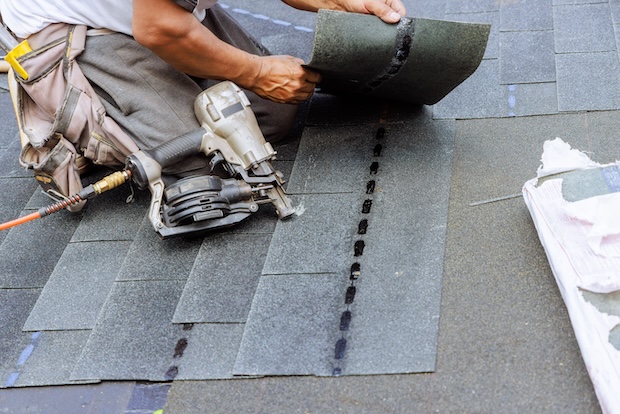
After a bad storm, it’s natural to worry about your roof. Missing shingles, fallen branches, hail, heavy snow, and strong winds can all leave homeowners wondering whether there’s damage, and whether they need to act fast.
Unfortunately, that urgency can also create an opportunity for dishonest contractors. Roofing scams often increase after severe weather, when homeowners are feeling pressure to make fast decisions and may not know exactly what damage they’re dealing with. While many roofing contractors are reputable, some use aggressive sales tactics or misleading promises to push unnecessary repairs or questionable insurance claims. That’s why it’s important to understand what roofing fraud is, how it can affect you, and what warning signs to watch for.
Roofing fraud happens when the condition of a roof or the cost of repairs is misrepresented in order to secure work or influence an insurance claim. In many cases, it starts with a contractor offering a “free inspection” after a storm and telling a homeowner they have serious damage, sometimes before the roof has been properly evaluated.
A contractor may claim your insurance will pay for a full roof replacement, promise you a “free roof,” or pressure you to sign paperwork right away so they can “handle everything.” In some cases, the damage may be exaggerated. In others, the repairs being recommended may not actually be necessary. What sounds like a helpful offer can quickly become a costly mistake if the contractor is more interested in generating work than protecting your home.
Many homeowners think the worst-case scenario is simply overpaying for repairs. In reality, roofing fraud can create much bigger problems.
If a contractor overstates damage, submits misleading information, or pressures you into unnecessary work, it can lead to:
Even homeowners who are trying to do the right thing can end up caught in the middle if they rely on the wrong contractor. That’s why it’s so important to ask questions before signing anything or allowing work to begin.
Not every contractor who shows up after a storm is acting in bad faith, but there are some common red flags homeowners should take seriously.
Be cautious if a contractor:
A reputable contractor should be willing to inspect the roof, explain what they found, provide an estimate, and give you time to make an informed decision. If someone is creating urgency or making big promises before the damage has been properly reviewed, that’s a good reason to pause.
If you believe your roof may have been damaged, there are a few simple steps that can help protect you:
And if you’re unsure whether the damage may be covered, or simply want another set of eyes on the situation, give Thorp & Trainer a call at 401.596.0146. We’re happy to help you better understand your coverage and what the next steps may look like before you commit to anything.